Cheap Liability Car Insurance in NJ
Compare Quotes Today & Discover the Best Low-Cost New Jersey Auto Insurance Options.
Compare Quotes in 2 Minutes
Powered by:

 Secured with SHA-256 Encryption
Bill Jones — insurance policy contributor
Reviewed for New Jersey’s 2026 minimum coverage requirements.
Drivers looking for cheap liability car insurance in NJ should compare quotes using the same policy type, liability limits, PIP choices, drivers, and vehicles. Premiums can vary by ZIP code, driving history, age, vehicle, coverage selections, discounts, and insurer underwriting, so a company that is inexpensive for one household may not be the cheapest for another.
New Jersey does not have a single policy that can accurately be called the cheapest for every driver. This guide explains the state’s Basic and Standard Policy structures, identifies insurers to include in a quote comparison, and shows how to compare price without overlooking important coverage differences.
Coverage note: CitizensInsurance.net is an independent insurance information and comparison website. It is not an insurance company, government agency, or official New Jersey state website. Rates, discounts, payment options, and eligibility vary by insurer, driver profile, policy, and state rules.
New Jersey’s Minimum Liability Laws
Vehicles registered in New Jersey generally must have the insurance coverages required by state law. New Jersey offers two principal policy structures: the Basic Policy and the Standard Policy.
Drivers should be careful when comparing what is sometimes called “liability-only” insurance in New Jersey. A quote can include liability coverage as well as mandatory or selected PIP and uninsured/underinsured motorist coverage, depending on the policy. The Basic Policy provides narrower protection, while the Standard Policy offers broader coverage choices and higher available limits.
Basic Policy
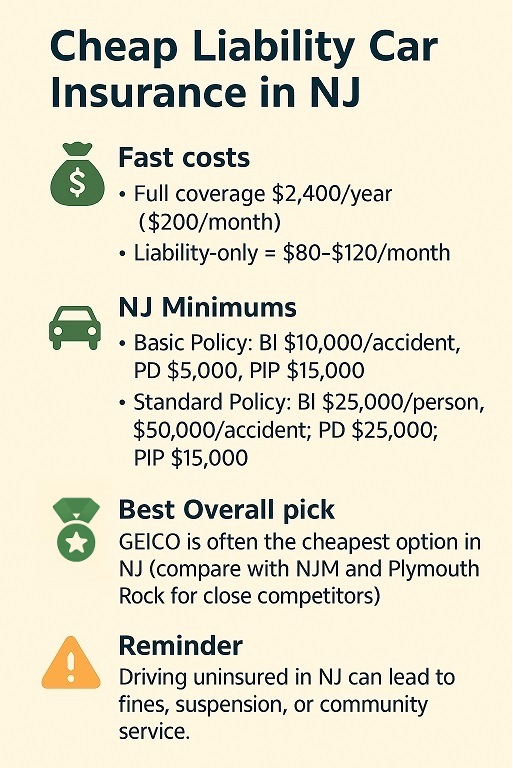
- Bodily injury liability is not included by default; $10,000 of coverage for all persons, per accident, is available as an option.
- $5,000 for property damage liability per accident.
- $15,000 of Personal Injury Protection (PIP) medical-expense coverage per person, per accident, with up to $250,000 for certain serious injuries identified by state rules.
The Basic Policy is intended as a lower-cost option but offers very limited protection. The state describes it as an option to consider for drivers with few family responsibilities and few real assets. Its low liability protection can leave a policyholder personally exposed after a serious at-fault accident, so price should not be the only consideration.
The Basic Policy is different from New Jersey’s Dollar-a-Day insurance program, formally known as the Special Automobile Insurance Policy (SAIP). SAIP is limited primarily to emergency medical treatment and does not provide liability coverage for injuries or property damage you cause.
Standard Policy Minimums
- $35,000 bodily injury liability per person.
- $70,000 bodily injury liability per accident.
- $25,000 property damage liability per accident.
- PIP medical-expense limits start at $15,000 per person, per accident, with higher limits available.
The Standard Policy offers broader protection and more flexibility. Drivers who own property or have savings should consider whether the statutory minimum would adequately protect those assets after a serious at-fault accident. An insurer or licensed New Jersey insurance professional can explain the available limits.
Quick NJ minimum coverage reminder
For Standard Policies issued or renewed on or after January 1, 2026, New Jersey’s minimum bodily injury liability limits increased to $35,000 per person and $70,000 per accident, while the minimum property damage liability limit remains $25,000. The Basic Policy is separate and remains much more limited.
New Jersey Minimum Coverage Comparison
| Coverage | Basic Policy | Standard Policy Minimum for 2026 |
|---|---|---|
| Bodily Injury Liability | Not included automatically; $10,000 per accident available as an option | $35,000 per person / $70,000 per accident |
| Property Damage Liability | $5,000 per accident | $25,000 per accident |
| PIP Medical Expense Limit | $15,000 per person, per accident* | Starts at $15,000, with higher options available |
| Higher Liability Limits Available? | Very limited | Yes |
*The Basic Policy provides up to $250,000 in PIP medical-expense coverage for certain serious injuries identified under New Jersey rules.
Companies to Include in a New Jersey Liability Quote Comparison
The companies below are examples of carriers or insurance providers New Jersey drivers may encounter. This is not a price ranking, and inclusion does not mean a company will be available or inexpensive for every applicant. Confirm current availability and compare quotes using identical drivers, vehicles, policy type, limits, PIP selections, and deductibles.
A national carrier with online quoting and policy-management tools. Include it in the comparison if it offers the requested coverage for your ZIP code and driver profile.
Offers online quotes and an optional telematics program. Ask how participation and driving data could affect the premium before enrolling.
Offers local-agent service and may provide multi-policy discounts when eligible. Compare the total cost of each policy rather than assuming a bundle is automatically cheaper.
A national carrier offering agent and online service. Ask which discounts actually apply to the quote and whether they continue at renewal.
A New Jersey-based insurer that offers personal auto coverage in the state. Its quote should be compared with the same limits and PIP selections used for other carriers.
Offers personal auto coverage in New Jersey. Review the insurer shown on the quote, payment schedule, fees, and coverage selections before comparing its price.
A national carrier with several potential discount categories. Availability and savings depend on eligibility and the details of the issued quote.
Offers auto insurance and usage-based options in some markets. Confirm which programs are currently offered in New Jersey and how driving data is used.
Eligibility is limited primarily to military members, veterans, and qualifying family members. Eligible drivers can include it in an otherwise equivalent quote comparison.
AAA Northeast may act as an insurance agency, while the policy itself is issued by the insurer named in the quote. Compare insurance separately from membership or roadside-assistance benefits.
Comparing GEICO and NJM in New Jersey
GEICO: National Online Option
Online quoting • Digital policy management • Eligibility varies
- Price: must be established with a current individual quote
- Fast online tools for quotes and policy management
- Discounts that may apply to students, military members, and safe drivers
- Broad availability for drivers comparing national carriers
One option to include in a like-for-like New Jersey quote comparison
GEICO provides online quoting and policy-management tools. Those features may suit drivers who prefer digital service, but they do not establish that GEICO is the cheapest option. Only a current quote using the same coverage selections as competing quotes can answer that question for a particular driver.
When comparing GEICO with a regional carrier, check the policy type, liability limits, PIP options, uninsured/underinsured motorist coverage, fees, discounts, and payment schedule. A lower initial payment is not necessarily a lower total premium.
NJM: New Jersey-Based Option
New Jersey presence • Direct quotes • Eligibility varies
- Regional strength: deep roots in New Jersey
- Price: must be established with a current individual quote
- Discounts that may apply for good students, safe drivers, and bundles
- Local market focus for New Jersey policyholders
A regional option to compare using the same coverage selections
NJM Insurance Group is based in New Jersey and offers personal auto insurance in the state. Its regional presence does not guarantee a lower premium, but it makes NJM a relevant company to include in a New Jersey quote comparison.
Review any available NJM discounts, but compare the final premium and coverage rather than the number of discounts advertised. Claims service and customer satisfaction should be evaluated with current, independent sources instead of assumed from the company’s regional status.
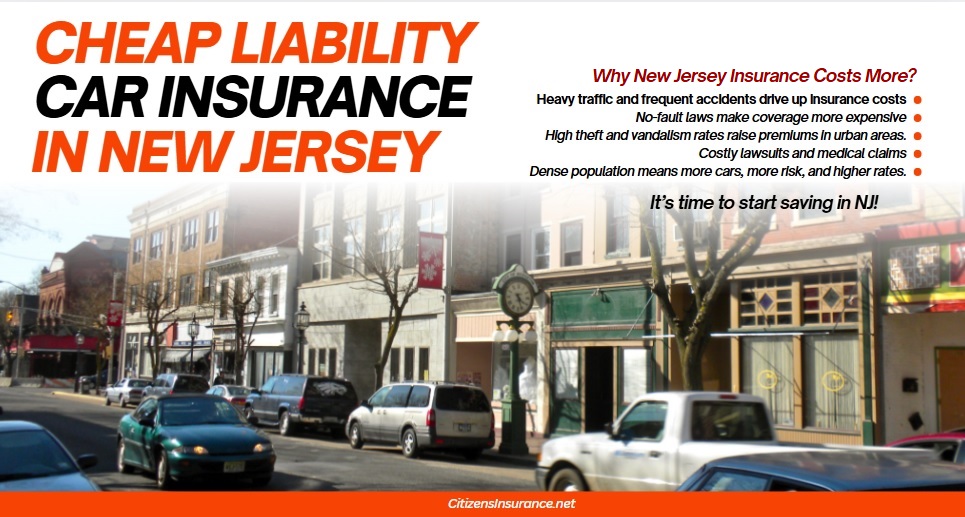
Why New Jersey Car Insurance Costs More
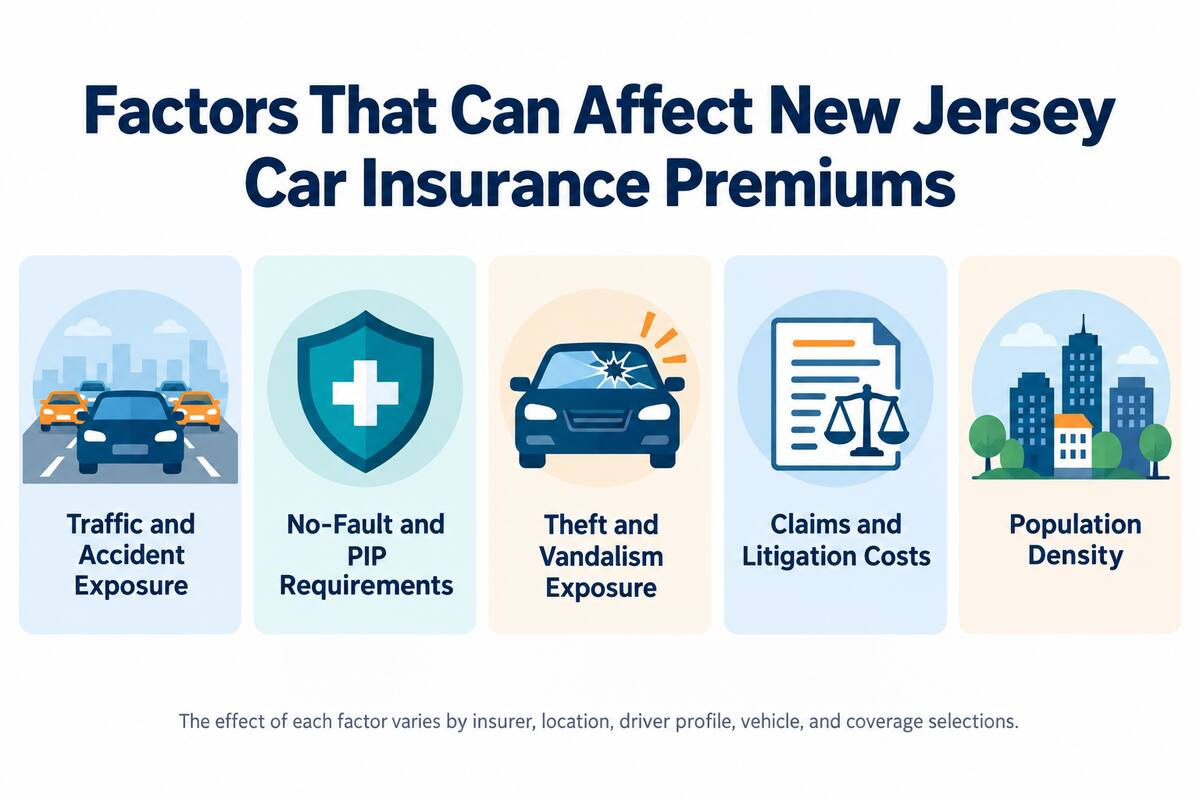
Insurers consider many factors when setting New Jersey auto premiums. The following conditions can contribute to claim frequency or severity, although this article does not attempt to quantify how much each factor changes an individual premium:
- Traffic and accident exposure – Congested roads can increase the opportunity for crashes and insurance claims.
- No-fault insurance laws – NJ is a no-fault state, meaning drivers must carry Personal Injury Protection coverage. This can raise costs compared to states without mandatory PIP.
- Theft and vandalism exposure – Insurers may consider location-specific claims experience when permitted by New Jersey rating rules.
- Claims and litigation environment – Liability settlements, medical bills, and disputed claims can affect insurer payouts and pricing over time.
- Population density – More vehicles and congestion can increase accident exposure.
Factors Driving New Jersey Insurance Costs
| Factor | How It Can Affect Premiums |
|---|---|
| High Accident Frequency | Can increase claim volume and insurer risk |
| No-Fault / PIP Mandates | Can increase medical claim costs |
| Theft & Vandalism | Can raise risk in certain ZIP codes |
| Claims and Litigation Environment | Can increase payout and defense costs |
| Population Density | Can increase congestion and crash exposure |
Liability Insurance for Teen Drivers in New Jersey
Adding a newly licensed teenager can change a household’s premium substantially. The actual effect depends on the driver, vehicle, insurer, discounts, and coverage selections. Families can ask insurers about the following options:
- Good Student Discounts – Teens who maintain a B average or higher may qualify for reduced rates with some insurers.
- Driver Training Courses – NJ-approved defensive driving or driver training classes may help reduce premiums depending on the insurer.
- Telematics Monitoring – Programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save may reward safe driving behavior.
- Household policy comparison – Compare adding the teen to an existing household policy with any separate-policy option for which the teen is eligible.
- Vehicle Choice – A modest, safe, reliable car can help keep liability premiums more manageable.
There is no universally cheapest insurer for a teen driver. Compare several quotes using the same teenager, household drivers, vehicle assignment, liability limits, PIP selections, and optional coverages.
Liability Insurance for Seniors in New Jersey
Age, mileage, driving history, vehicle, location, and insurer rating methods can affect an older driver’s premium. Rather than assuming age alone will increase the rate, ask each insurer which discounts and rating factors apply:
- AARP Auto Insurance Program (The Hartford) – Senior-friendly policies may include safe-driving rewards or member-related benefits.
- Membership benefits – Evaluate roadside assistance and other membership services separately from the insurance policy and premium.
- Defensive Driving Discounts – Seniors who take refresher driving courses may qualify for premium reductions with some insurers.
- Low-Mileage Discounts – Retired drivers who use their cars sparingly may qualify for reduced premiums.
Older drivers should compare quotes periodically using identical coverage selections. Drivers with retirement savings, home equity, or other assets should also consider whether minimum liability limits provide sufficient protection.
Compare Quotes in 2 Minutes
Compare Insurance Quotes and Save!
 Secured with SHA-256 Encryption
How to Save Money on Liability Car Insurance in New Jersey
Premiums can vary among insurers even for the same driver. Use a controlled comparison:
- Get at least three quotes on the same day, using the same drivers, vehicles, coverage limits, PIP selections, and deductibles.
- If the initial payment is a concern, review how low-initial-payment and “first month free” car insurance offers may be structured. Compare the total premium and all installment fees, because a smaller first payment does not necessarily mean cheaper insurance.
- Bundle auto with homeowners or renters insurance when eligible, but compare the combined cost against separate policies before assuming the bundle is cheaper.
- Consider a telematics program if you are comfortable sharing driving data. Ask what information is collected, how long it is retained, and whether poor driving results could increase the premium.
- Compare paying the premium in full with an installment plan. Include installment, processing, late-payment, and reinstatement fees when calculating the total policy cost.
- Maintain continuous coverage. Before changing insurers, confirm that the new policy is active so that canceling the previous policy does not create an unintended lapse.
- Ask about discounts available for your actual profile, such as multi-vehicle, good-student, defensive-driving, employer, association, paperless, or automatic-payment discounts. Confirm whether each discount continues at renewal.
- If you purchase collision or comprehensive coverage, consider whether a higher car insurance deductible would reduce the premium. Choose only a deductible you could afford to pay after a covered loss.
Before switching, confirm the new policy is active and avoid creating a lapse in coverage.
Common Pitfalls to Avoid When Insuring Your Vehicle in NJ
Chasing the cheapest rate sometimes leads drivers into costly mistakes. Here are pitfalls to watch for:
- Ignoring MVC compliance – If your insurer does not properly report coverage or you cannot provide proof of insurance when required, you may face fines, suspension, surcharges, or other penalties.
- Choosing the Basic Policy when you have assets – Minimum limits may leave you exposed after a serious accident.
- Forgetting high-risk or assigned-risk rules – If you have serious violations, suspensions, at-fault accidents, or insurance eligibility points, you may have fewer voluntary-market options and may need to ask about the New Jersey Personal Automobile Insurance Plan (PAIP).
- Overlooking hidden fees – Some low-premium plans add installment, processing, or reinstatement charges that can make them more expensive long-term.
FAQs About Liability-Only Auto Insurance in NJ
For a Standard Policy issued or renewed on or after January 1, 2026, New Jersey minimum liability limits are generally $35,000 bodily injury per person, $70,000 bodily injury per accident, and $25,000 property damage per accident. The Basic Policy is separate and more limited.
No. If your vehicle is registered in New Jersey, it generally must be insured. Contact the NJ MVC or your insurer before canceling coverage on a registered vehicle.
It depends on your profile, but GEICO, NJM, Progressive, State Farm, and USAA if eligible, are often worth comparing. The cheapest company for one driver may not be the cheapest for another.
Usually not. It is often cheaper to add a teen driver to a parent’s policy, but the best option depends on household, vehicle, insurer rules, and eligibility.
Not always. Some seniors may see higher rates with age, but many insurers offer discounts for defensive driving, low mileage, or policy bundling. Comparison shopping is crucial.
The Final Word on Cheap Liability Car Insurance in New Jersey
The lowest-priced New Jersey quote is not necessarily the policy with the lowest total annual cost or the most appropriate protection. Compare the Basic and Standard Policy structures carefully and use identical coverage selections for every quote.
Drivers may choose to compare national and regional carriers, including any insurer for which they are eligible. The result applies only to the drivers, vehicles, ZIP code, coverage selections, discounts, and date shown on each quote.
Before purchasing, review the liability limits, PIP selections, uninsured/underinsured motorist coverage, exclusions, fees, and payment schedule. Consider whether the minimum limits would leave your income or assets exposed after a serious accident.
You can use the Citizens Insurance comparison form as one way to request quotes. It may not include every insurer, and a submitted request does not guarantee a particular price, coverage, or eligibility.
References
- New Jersey Motor Vehicle Commission. Insurance Requirements.
- New Jersey Department of Banking and Insurance. New Jersey’s Basic Auto Insurance Policy.
- New Jersey Department of Banking and Insurance. Standard Auto Insurance Policy.
- New Jersey Department of Banking and Insurance. Bulletin No. 25-06: Auto Insurance Coverage Limits Pursuant to P.L.2022, c.87.
Compare Quotes in 2 Minutes
Secured with SHA-256 Encryption
OUR WEBSITE
TRUST & AUTHORITY

Featured Articles
SEARCH
Looking for something specific? Use the search bar below to find answers to your questions!